
Owner Financing Homes in Maryland
Owner financing homes in Maryland settle with a title company or attorney, and the deed is recorded in your name in the county land records.
- No minimum credit score
- First-time buyer transfer tax break
- Baltimore and the surrounding counties
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
How owner financing works in Maryland
Source: Median price from Redfin, September 2026.
In Maryland, closing is called settlement, and it's handled by a title company or a settlement attorney. With owner financing you sign a promissory note and a deed of trust, and your deed is recorded in your name in the land records of the county circuit court.
Maryland homes sell fast and close to asking price, so being ready matters. A qualification letter from us lets you make an offer the day you find the house. We negotiate, set the terms and get you to settlement without a bank's underwriting timeline.
Your payment is fixed. There's no balloon and no penalty for paying early, so you can refinance into a conventional loan once your credit catches up. Start with how the program works.
Closing costs in Maryland
Maryland's closing taxes are among the highest in the country and vary by county, so we price them into your numbers before you choose a home. First-time Maryland buyers who will live in the home get a break on the state transfer tax.
| Cost | Rate | Who usually pays |
|---|---|---|
| State transfer tax | 0.5% of the price, with a break for first-time Maryland buyers | Shared or set by your contract |
| County transfer tax | Varies by county | Set by your contract |
| Recordation tax | Varies by county | Set by your contract |
| Title, settlement and recording fees | Set by the settlement company | Set by your contract |
Property taxes and the Homestead Tax Credit
As the owner you pay county property taxes, and Baltimore City sets its own. Maryland's Homestead Tax Credit limits how much your taxable assessment can rise each year on your principal residence: 10 percent for state taxes, and many counties set an even lower cap.
You apply once, and it stays in place while you live there. It only goes to the owner of record, so a rent to own tenant can't claim it.
Maryland cities we cover
Local guides with home prices, neighborhoods and where your deed gets recorded.
Baltimore, MD
Source: Redfin housing market data, three months ending September 2026.
Don't see your city? You can pick a home anywhere in Maryland we can negotiate. Tell us where in the form.
Who buys with owner financing in Maryland
These are the Maryland buyers we hear from most. If one sounds like you, the program was built for you.
Healthcare and university workers
Hospital systems and universities around Baltimore employ thousands on contracts, residencies and shift work. Real income, unusual paperwork.
Federal contractors and military families
Fort Meade, Aberdeen and the contractor economy around them bring buyers who move often and want to own between assignments.
First-time buyers facing high closing costs
Maryland's transfer and recordation taxes add up. We map them out with you so there are no surprises at settlement.
Buyers with a past foreclosure
Maryland had a lot of foreclosures a decade ago. If yours is behind you, it isn't held against you here.
Three steps to a Maryland home.
How a Maryland purchase moves from first call to keys.
Get qualified
We go over income and down payment. Your letter is good for up to 12 months, which matters in a market where homes sell near asking.
Pick your Maryland home
Choose three homes. We negotiate and structure the note and deed of trust.
Go to settlement
A title company or settlement attorney handles settlement, records your deed with the circuit court land records, and you get the keys.
Owner financing vs rent to own in Maryland
Rent to own deals in Maryland leave the deed with the seller, which also means the seller keeps the Homestead Tax Credit and any first-time buyer tax break goes unused. If the seller falls behind, the tenant has very little protection.
Owner financing records the deed in your name at settlement. Read the full comparison.
Cash to close on a Maryland home
The calculator starts at Maryland's September 2026 median sale price of $428,768. Move it to the price you have in mind.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
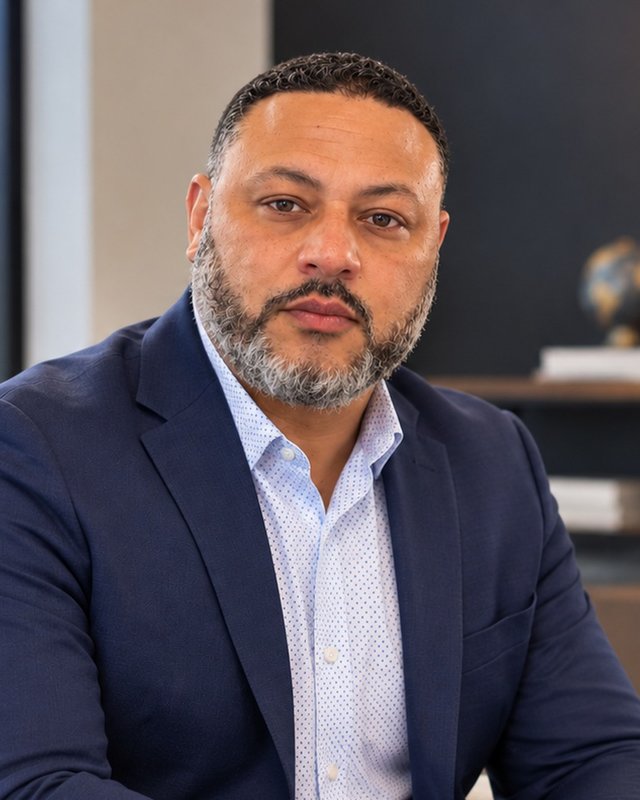
Your Maryland contact
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy works with Maryland buyers in Baltimore and the surrounding counties, with every settlement handled by a title company or settlement attorney.
Every Maryland purchase closes with a Maryland title company or settlement attorney, and your deed is recorded with the circuit court land records in your name.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify for a Maryland home.
Tell us where in Maryland you want to buy and what you can put down. Freddy will reach out within 24 hours.
- Closing with a Maryland title company or settlement attorney.
- Deed recorded with the circuit court land records.
- You can apply for Maryland's Homestead Tax Credit, which caps yearly assessment increases.
- No minimum credit score.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Maryland owner financing questions
How does owner financing work in Maryland?
You sign a promissory note and a deed of trust at settlement, and your deed is recorded in your name in the county land records. A title company or settlement attorney handles settlement.
What closing taxes does Maryland charge?
Maryland charges a state transfer tax of 0.5 percent of the price, plus county transfer and recordation taxes that vary by county. First-time Maryland buyers who will live in the home get a break on the state transfer tax.
What is the Maryland Homestead Tax Credit?
It limits how much the taxable assessment on your principal residence can rise each year: 10 percent for state taxes, often less for county taxes. You apply once.
Can I buy in Baltimore City with owner financing?
Yes, in the neighborhoods where homes sell for $250,000 or more, such as Hamilton, Lauraville and Highlandtown. The city's median sale price was about $230,000 in September 2026, so many buyers also look just over the county line.
How fast can I settle?
Once we agree on a home and terms, settlement usually takes 30 to 45 days.
What credit score do I need?
There is no minimum credit score. We qualify Maryland buyers on income and down payment.
Compare the other states
Florida
Georgia
Alabama
North Carolina
South Carolina
Median prices: Redfin, September 2026.
Ready to own in Maryland?
Find out in about a minute whether the program fits you.