
Buy a Home After Bankruptcy or Foreclosure
You can buy a home after bankruptcy or foreclosure without waiting out a bank's two to seven year rule. We look at what your finances look like now.
- No bank waiting periods
- No minimum credit score
- Deed in your name at closing
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
How long after bankruptcy can I buy a house?
With a bank, the wait is usually two to four years after a Chapter 7 discharge and up to seven years after a foreclosure, depending on the loan type. In this program there's no fixed waiting period. If your income is steady and you have a down payment, we can talk now.
What we care about
We care about what your finances look like today, not what happened to you in a hard year. A bankruptcy that cleared old debt can leave you with lower monthly bills than before, which makes a payment easier to carry.
What we look for is steady income, a down payment of normally 20 percent of the price we negotiate, and a clean recent record. One bankruptcy or one foreclosure in the past is not a dealbreaker. A pattern of them is.
Documents to have ready
Your bankruptcy discharge papers or foreclosure date, recent bank statements, proof of income and proof of your down payment. Being upfront about what happened makes the conversation faster.
A path back to a bank loan
Owning the home and paying on time while your waiting period runs out puts you in a strong position. When you become eligible for a conventional loan, you can refinance with no prepayment penalty.
Chapter 7 vs Chapter 13
A Chapter 7 discharge wipes out most unsecured debt, which can leave your monthly budget lighter than before. A Chapter 13 plan may still be active when you apply. Tell us which one you filed and when, and bring the paperwork. Either one can work with steady income and a down payment.
How it works for you, start to finish.
Three steps from first call to keys, built around your situation.
Tell us what happened
Bring your discharge papers or foreclosure date. Being upfront makes the conversation short.
Show steady income since
We look at how you've handled bills and rent since the filing or foreclosure.
Own now, refinance when eligible
Close with the deed in your name. When the bank's waiting period ends, refinance if you want.
Who you're talking to
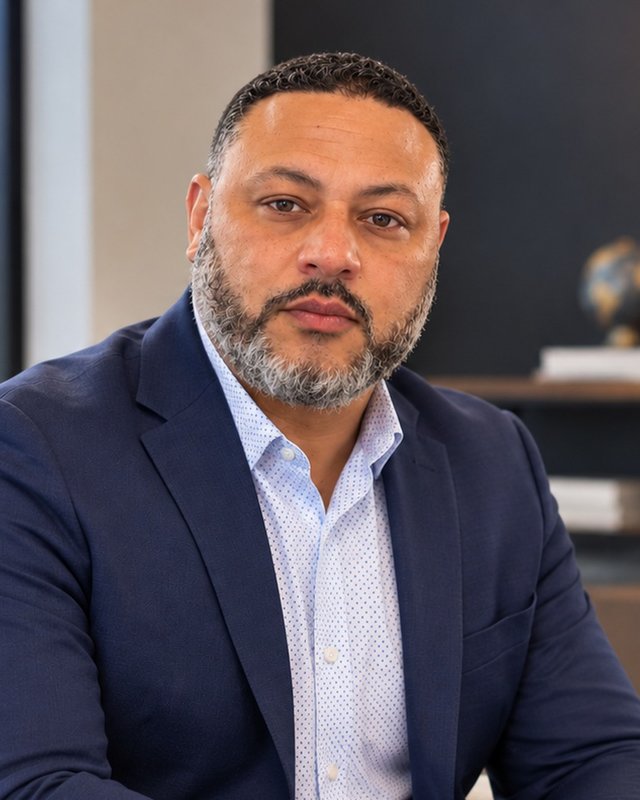
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy cares about what your finances look like now. A hard year in the past is one part of your story, not the whole thing.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours.
- No bank waiting period.
- One past filing isn't a dealbreaker.
- Deed in your name at closing.
- Refinance when you become eligible.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Questions we hear about this
Can I buy a house after bankruptcy?
Yes. In this program there's no fixed waiting period. We look at your income and down payment now.
Can I buy a house after a foreclosure?
Yes. A past foreclosure isn't a dealbreaker if your finances are steady today.
How long do banks make you wait?
Usually two to four years after a Chapter 7 discharge and up to seven years after a foreclosure, depending on the loan.
Will I pay a higher rate?
Your rate and terms are set when you qualify, based on your situation and the home.
What disqualifies me?
A pattern of not paying, such as repeat bankruptcies or evictions.
Ready to stop renting?
Find out in about a minute whether the program fits you.