
Owner financing homes, without a bank loan.
Owner financing homes in Florida, Georgia, Alabama, the Carolinas and Maryland. You pick the home, we arrange the financing, and the deed is yours at closing.
- No minimum credit score
- Self-employed, 1099 and ITIN buyers welcome
- No balloon payment, no prepayment penalty
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Good people in complicated situations.
Banks say no for reasons that have little to do with whether you can afford a house. These are the people we work with. See everything we look at.
Your credit doesn't tell the whole story
A low score, old collections or no credit file at all. We look at the full picture instead of one number.
Self-employed or 1099
Your income is real, it just doesn't fit a W-2 box. We know how business income actually works.
A bankruptcy or foreclosure behind you
We care about what your finances look like now, not what happened years ago.
New to the United States
You're building a life here and need somewhere stable. We work with ITIN holders and non-traditional documents.
You changed jobs recently
Lenders want two years with the same employer. We look at whether the income is steady.
Done with rent to own offers
Own the home at closing instead of renting with a promise. Build a payment record and refinance when the timing works.
Three steps to your home.
No paperwork maze and no three month wait to hear back.
Get qualified
We go through your income, your down payment and your situation. You get a qualification letter good for up to 12 months, so you can make an offer the same day you find a home you want.
Pick your home
Choose three homes you would actually live in. We approach your first choice, negotiate the best price we can get and structure the offer for you. Listed homes, for sale by owner, builder inventory and off-market homes all work.
Close and get your deed
We close through a title company or a closing attorney. You get the keys and a deed in your name, and a third-party servicer handles your payments with an online portal you can check any time.
Owner financing and rent to own are not the same thing.
People mix these up all the time, and the difference decides who actually owns the house if something goes wrong. Read the full comparison.
| Question | This program | Rent to own or lease option | Waiting for a mortgage |
|---|---|---|---|
| When you own the home | At closing, on day one | Only if you qualify and exercise the option later | After a lender approves you |
| If the seller hits money trouble | Your deed is already recorded, so the home is yours | A bankruptcy, divorce, tax lien or judgment against the seller can cost you the home, even if you paid on time | Does not apply |
| Credit score needed | No minimum | Varies by seller | Usually 620 or higher |
| Self-employed income | Bank statements or tax returns | Varies by seller | Usually two years of documented history |
| Money up front | 20% down, credited to the purchase | An option fee, often lost if you don't buy | 3% to 20% down, plus closing costs |
| When you build equity | With your first payment | Not until you buy the home | Once you close |
| Which home you can get | Any home you pick that we can negotiate, $250,000 and up | Whatever that one landlord owns | Any home the lender will approve |
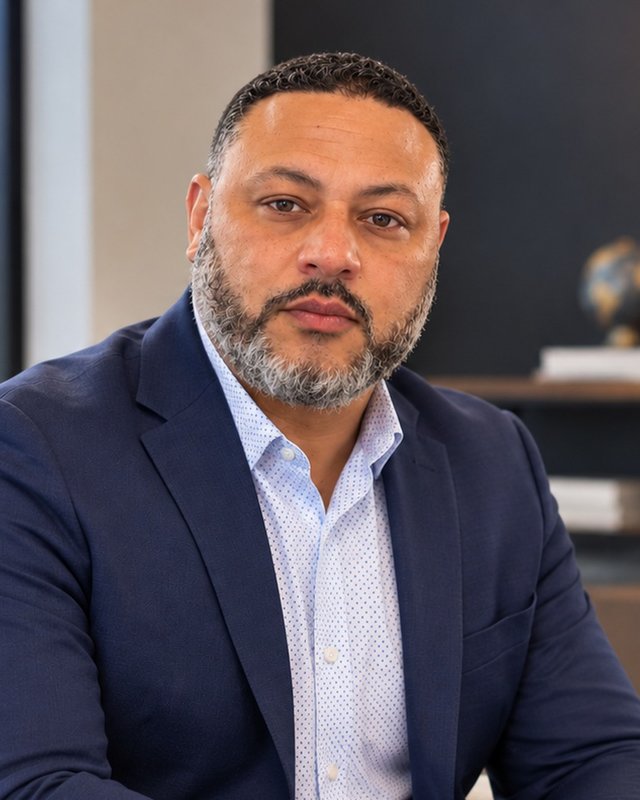
Who you're talking to
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
"If you can afford the house, there should be a path to it."
My name is Freddy E.. I've been in real estate since 2010, I hold a finance degree from Florida International University, and I spent years in business-to-business sales at Black & Decker, Ryder and Penske Logistics before going into real estate investing full time.
Since 2024 I've helped more than 20 families into homes a bank told them they couldn't buy. I structure the deal, negotiate the price, coordinate everyone involved and stay with you through keys, move-in and deed. You won't get handed off to a call center.
Freddy E.Founder, Sold With Financing
In a buyer's words
"We moved from Louisiana to Illinois looking forward to a new journey for our family. We were being turned down for a chance to purchase a home due to credit not being where they wanted it to be. That was until we met Mr Freddy. He gave us a chance to purchase a home through leasing. After 2 years of Leasing to Own, Mr Freddy called with excitement in his voice and wanted to see if we were ready to become homeowners. He made phone calls, on our behalf, in finding the right people to guide us into the home buying process. In less than a month, we were becoming the proud owners of a home for the first time."
See how much cash you need.
Move the slider to a home price. You'll see the 20 percent down payment and typical closing costs. Your rate and monthly payment are set when you qualify.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
Who this is not for.
We turn people down, and it's fairer to tell you here than after you've filled out a form.
This isn't for you if what you actually want is to rent with a loose promise to buy someday. You'd be buying a home, with the obligations that come with it.
It's also not for you if there's a pattern of not paying: repeat evictions, repeat bankruptcies, or a habit of walking away from financial obligations. We run a standard background check, including criminal and payment history, as part of qualifying. Decisions aren't based on credit, and any criminal history is reviewed one case at a time.
Where we help buyers.
Six states, each with its own closing rules and its own tax break for people who own the home they live in.
Florida
Georgia
Alabama
North Carolina
South Carolina
Median prices: Redfin, September 2026.
Straight answers.
Do I actually own the home from day one?
Yes. You close with a title company or a closing attorney and receive a deed in your name at closing. You are the owner of record from that day, while you are still paying off the financing.
How is this different from rent to own?
In most rent to own or lease option deals you don't own anything yet. If the seller runs into a bankruptcy, a divorce, a tax lien or a judgment, you can lose the home even though you paid every month on time. With this program the deed is recorded in your name at closing, so the house is legally yours.
What credit score do I need?
There is no hard minimum. We look at your income, your stability and how much you can put down. A low score by itself won't disqualify you, so don't let it stop you from asking.
How much do I need for a down payment?
The standard is 20 percent, and exceptions are reviewed one by one. Your down payment is figured on the price we negotiate, not a higher adjusted number. Any earnest money you put up when making an offer is credited toward your down payment at closing.
Do I pay fees or commissions?
There's no application fee and no origination fee. You pay customary closing costs, typically 2 to 3 percent of the price depending on the state. Your down payment goes toward the purchase, and everything is disclosed in writing before you sign.
Can I refinance into a regular mortgage later?
Yes, and we want you to. Once you have a record of on-time payments and equity in the home, you're in a much stronger position with a traditional lender. There is no prepayment penalty.
I'm self-employed. Does that hurt me?
No. We'll ask for bank statements or tax returns to confirm you can handle the payment, and that's the extent of it. A W-2 job isn't required.
How fast can I get into a home?
Closing typically takes 30 to 45 days once we've agreed on a home and terms. Your deposit, income verification and background check are what set the pace.
Who collects my monthly payment?
A third-party loan servicing company. You get your own login and can see every payment you've made, any time. That record matters when you refinance later.
See every question we get asked
Tell us what you're looking for.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours to talk through your situation, your work, your income and your down payment.
- The deed is in your name at closing.
- There is no minimum credit score.
- Self-employed and 1099 income both count.
- ITIN holders are welcome.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Ready to stop renting?
Find out in about a minute whether the program fits you.