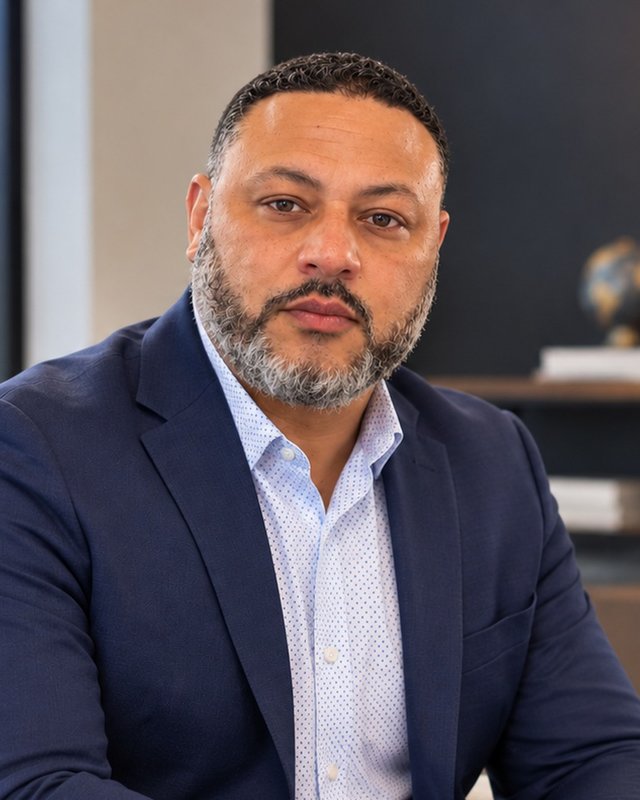
About Freddy E. and Sold With Financing

Sold With Financing is Freddy E.'s owner financing program for people with real income and a real down payment who still get told no by a bank. Since 2024 it has helped more than 20 families into homes.

Freddy E., founder of Sold With Financing

Why Freddy started this

"The banking system is broken," Freddy says. In his experience, banks are "not really looking at the full picture of the individual." A buyer with steady income and money saved can still be "just a number to a bank that has to fit in a cookie-cutter box."

He kept meeting those buyers: veterans, business owners, people new to the country, people whose credit took a hit from something that's long behind them. "There's a big need in the market," he says. Sold With Financing is his answer to it.

  • In real estate since 2010
  • Finance degree, Florida International University
  • 20+ families into homes since 2024

Before real estate

Freddy studied finance at Florida International University, then spent years in business-to-business sales at Black & Decker, Ryder Transportation and Penske Logistics. That work taught him how companies size up risk, and how often a good customer gets turned away by a rule that doesn't fit them.

He has worked in real estate since 2010. Over the years he has closed deals across Florida, Illinois, Georgia, Alabama and the Carolinas, which is why the program covers the markets it does.

Why this is owner financing, not rent to own

"With rent-to-own, they don't get the deed," Freddy says. "They basically get the option to own the property one day. With my program, the buyer is getting the deed, which is ownership of the house."

The difference matters most when something goes wrong. In a rent to own deal, the seller can change their mind at any time and keep the deposit. Here, your protection is a recorded deed in your name, payments handled at arm's length by a servicing company, and a portal where you can log in any time and see the payments being made. See the full comparison.

What every buyer gets

These are the parts of the program Freddy won't change, whatever state you buy in.

  • You get the deed at closing. You own the home from day one.
  • Your deposit sits in third-party escrow and is refunded if the deal doesn't close.
  • A licensed loan originator verifies your income, and a third-party company services the loan, with a portal where you can see every payment.
  • Every deal closes with a title company or a real estate attorney.
  • You pick the home, including homes listed with an agent.
  • ITIN buyers are accepted, and decisions aren't based on credit.
  • Buyers have gone on to refinance into VA and conventional loans.

Where Freddy works

Big metro areas in Florida, Georgia, Alabama, North Carolina, South Carolina, Maryland.

  • Florida: Tampa, Orlando, South Florida
  • Georgia: Atlanta, Augusta, Athens
  • Alabama: Birmingham, Tuscaloosa, Montgomery, Huntsville
  • North Carolina: Charlotte, Raleigh, Greensboro, Durham, Winston-Salem
  • South Carolina: Charleston, Columbia, North Charleston, Mount Pleasant
  • Maryland: the Baltimore area

Freddy speaks Spanish fluently, so calls and emails can be in English or Spanish. Ver este sitio en español.

Three buyers, three bridges to a bank loan

Every one of these buyers used owner financing to get into a home first, then refinanced once a bank would say yes.

William A., Orlando: a business owner who needed time

William owns a business. His income was real, but his business taxes needed cleaning up, and no bank would lend until they were. That could have meant years of renting.

Instead he bought a $380,000 Orlando home with $65,000 down, about 17 percent, an exception Freddy reviewed on its own merits. He closed in under 40 days and paid about $2,100 a month. Forty months later, with his taxes in order, he refinanced into a conventional loan.

$380,000Purchase price
$65,000Down payment
About $2,100Monthly payment
40 monthsUntil he refinanced

Dale H., Birmingham: a veteran a bank wouldn't see

"The buyer that we helped in Alabama is a prime example," Freddy says. "This is a person who served our country. He had a situation with an ex-wife that completely destroyed his credit, and he couldn't even walk into a bank for a loan or get a VA loan."

Dale was finishing a 20-year Army career and moving his family from Hawaii to Alabama. He bought a three-bedroom, two-bath home for $239,000 with $40,000 down, about $1,700 a month, and closed in about 50 days around the move. His family is still in the home, and his VA refinance is in progress.

$239,000Purchase price
$40,000Down payment
About $1,700Monthly payment
VA refinanceIn progress

Travis K., Peoria: a 520 credit score and a VA loan 30 months later

Travis is a retired veteran whose credit score sat around 520. Freddy already owned a four-bedroom, two-bath house in Peoria, Illinois, and after 45 days of marketing it, Travis was the buyer.

He put $20,000 down on the $169,000 home and paid $1,680 a month. After 30 months of payments in his own name, he refinanced into a VA loan. This was a past deal outside today's markets and below the program's current $250,000 starting point, but it's the clearest example of the program working as a bridge.

About 520Credit score
$20,000Down payment
$1,680Monthly payment
30 monthsUntil his VA refinance
What buyers say

"We moved from Louisiana to Illinois looking forward to a new journey for our family. We were being turned down for a chance to purchase a home due to credit not being where they wanted it to be. That was until we met Mr Freddy. He gave us a chance to purchase a home through leasing. After 2 years of Leasing to Own, Mr Freddy called with excitement in his voice and wanted to see if we were ready to become homeowners. He made phone calls, on our behalf, in finding the right people to guide us into the home buying process. In less than a month, we were becoming the proud owners of a home for the first time."

Mari FredricksHomeowner, Illinois

See if you qualify.

Tell Freddy what you're looking for. He replies within 24 hours.

  • The deed is in your name at closing.
  • There is no minimum credit score.
  • Self-employed and 1099 income both count.
  • ITIN holders are welcome.

See if you qualify

Takes about a minute. Freddy replies within 24 hours.

The program normally needs 20% of the price down. Exceptions are reviewed one by one.

We never sell or rent your information, and we never ask for your Social Security or ITIN number here.

Ready to stop renting?

Find out in about a minute whether the program fits you.

Email See If I Qualify

We use analytics to see which pages help buyers and where our form is confusing. You can turn it off. The site and the form work the same either way.

EssentialRemembers this choice. Always on.

Details in our Cookie Policy.