
How Owner Financing Works
How owner financing works with us: you qualify on income and down payment, pick the home, and close with the deed recorded in your name.
- Qualification letter good for 12 months
- Close in about 30 to 45 days
- Fixed payment, no balloon
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
1. Get qualified
Fill out the form or call. Freddy goes through your income, your down payment and your situation, usually in one conversation. We look at whether you can comfortably carry the payment, not at a credit score cutoff.
Qualifying is based on your down payment and your monthly income, and a licensed loan originator verifies the income. If it fits, you get a qualification letter good for up to 12 months. That letter is what lets you make an offer the same day you find a home, the way a buyer with a bank pre-approval would.
2. Pick your home
Choose three homes you would genuinely live in, priced from $250,000 up with no upper limit. Agent-listed homes, for sale by owner, new construction and off-market homes from Freddy's investor network are all possible. Three picks means there's a backup if a seller says no.
We approach your first choice, negotiate the best price we can get and structure the offer on your behalf. Your down payment is figured on the price we negotiate. Your deposit goes to a third-party title company or attorney, not to us. It's held in escrow, it's due within 48 hours of clear to close, and it's refunded if the deal doesn't close.
3. Close and get your deed
Closing happens through a title company or a qualified closing attorney, depending on the state. You sign a promissory note and the security document your state uses: a mortgage, a deed of trust or, in Georgia, a security deed. The deed is recorded in your name with the county the same day.
From there you make one fixed monthly payment on a 30-year, fully amortized note. A third-party servicing company collects it, and you can log into its portal any time to see every payment. There is no balloon payment and no prepayment penalty. You pay property taxes and insurance like any owner, and you can refinance into a regular mortgage whenever you're ready.
What to have ready
Having these together makes your first conversation faster. You won't need everything on day one.
- A valid government ID or passport
- Your Social Security number or ITIN, shared during the secure qualifying process, never on this website
- Proof of income: bank statements, pay stubs, tax returns, 1099s or a profit and loss statement
- Proof of your down payment funds
- Your current address and rental history
How long it takes
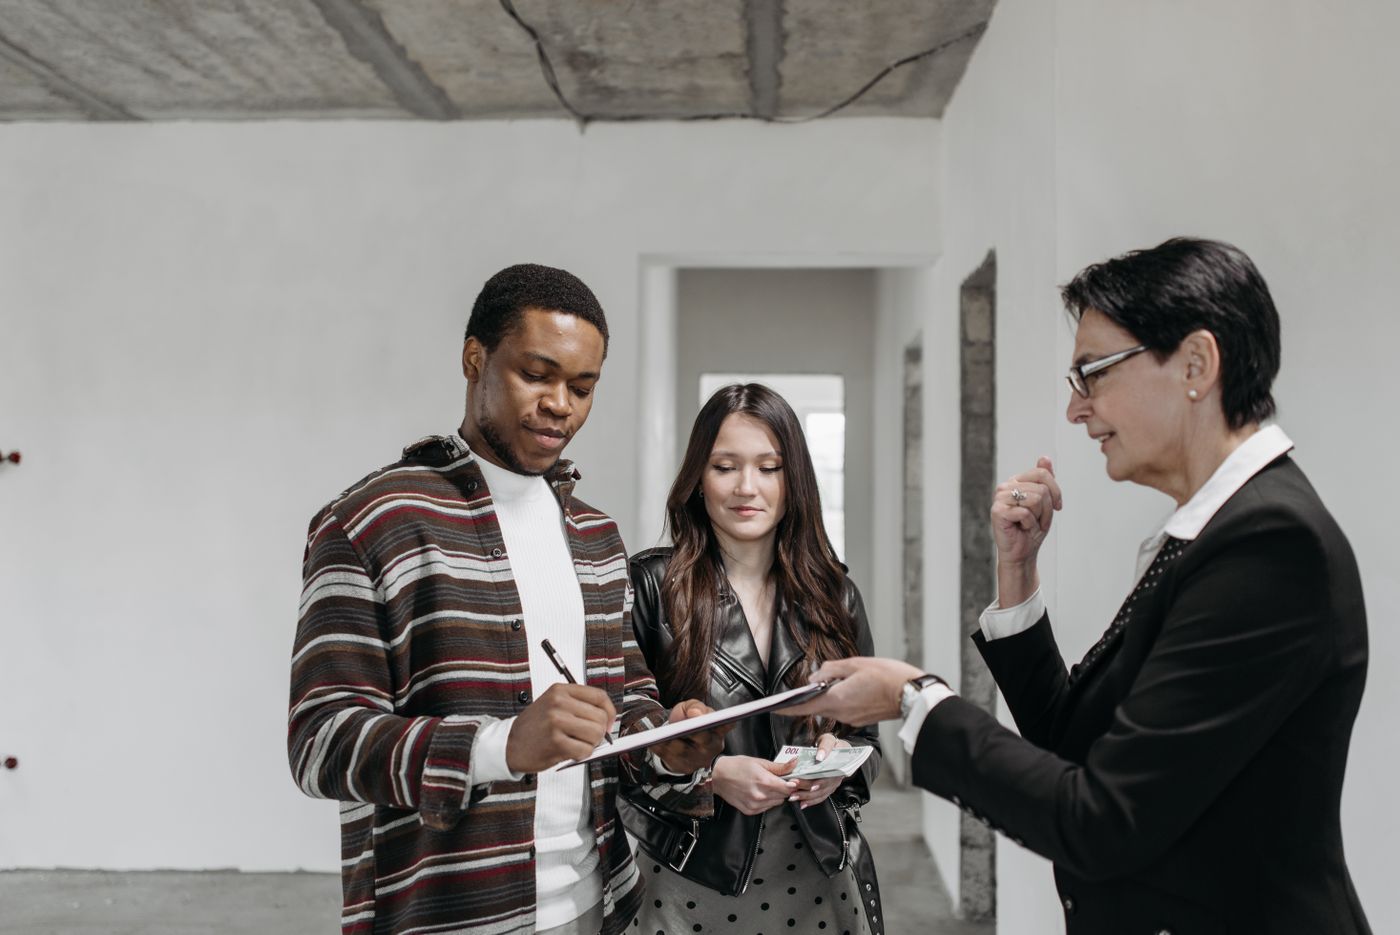
Qualifying usually takes a day or two once we have your documents. Finding the home is up to you and the market. Once we agree on a home and terms with the seller, closing typically takes 30 to 45 days. Your deposit, income verification and background check are the three things that set the pace.
What it costs
There's no application fee and no origination fee. Your down payment goes toward the purchase, and you pay customary closing costs, typically 2 to 3 percent of the price depending on the state. After that come the normal costs of owning a home: property taxes, insurance and upkeep. Each state page breaks down its closing costs. Everything is disclosed in writing before you sign.
Run the numbers before step one
See how much cash a home at your price takes to close, then bring that number to your first call.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
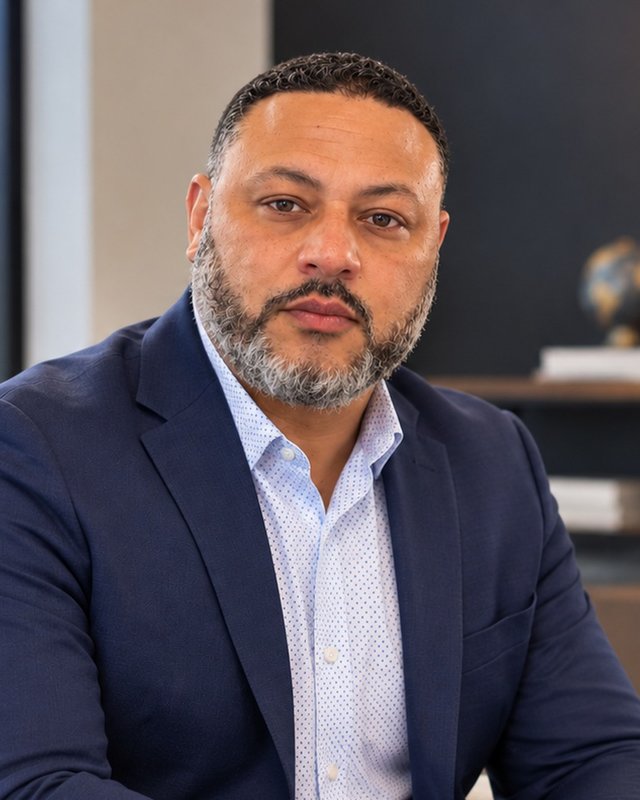
Who walks you through it
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy handles each step himself: the qualifying call, the negotiation with the seller and coordination with the title company or attorney. You have one person to call from start to finish.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
Questions about the process
How long does it take to get qualified?
Usually a day or two after we have your documents. Many buyers get an answer in the first conversation.
Who holds the note after closing?
The note is held by the party providing the financing. Your payment terms are in writing before you sign, and the deed is in your name either way.
What happens if I want to sell before the note is paid off?
You can sell like any owner. The note is paid off from the sale proceeds at closing, and you keep the rest.
Are taxes and insurance included in my payment?
That depends on how your closing is set up. Some buyers pay them with the monthly payment and some pay them directly. It's spelled out before you sign.
Ready to stop renting?
Find out in about a minute whether the program fits you.