
Home Loans for Self-Employed Buyers, Without the Bank
Buying a house self-employed is hard with a bank and simple here. We read your bank statements or tax returns, and a W-2 job isn't required.
- Bank statements or tax returns
- 1099, gig and small business income
- No two-year W-2 rule
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Why banks turn down self-employed buyers
Banks qualify self-employed buyers on the income left after write-offs on their tax returns. A business that clears $90,000 can show $35,000 on paper after expenses, and the bank uses the smaller number. Many lenders also want two full years of returns from the same business.
That system punishes people for running their business well. Owner financing doesn't use it.
How we look at your income
We ask for bank statements or tax returns, whichever tells the real story, to confirm you can comfortably handle the payment. Recent business or personal statements usually show it clearly, and a profit and loss statement works too. 1099 income, gig work, commission and cash businesses that deposit their income all count.
Rideshare drivers, truckers, contractors, salon owners, real estate agents and freelancers are some of the buyers we see most.
Documents to have ready
Recent bank statements, your most recent tax returns if you have them, any 1099s, a profit and loss statement, a business license if you have one, and proof of your down payment. If you run cash through your business, deposit it consistently so your statements match what you earn.
Own now, refinance later
After a stretch of on-time payments and another year or two of business history, a bank-statement loan or conventional mortgage can pay off the note. There's no prepayment penalty.
Tips before you apply
Keep business and personal money in separate accounts if you can. Deposit cash income regularly instead of holding it. Pull your recent statements and look at your average monthly deposits. That average, not your best month, is the number that sizes your payment.
How it works for you, start to finish.
Three steps from first call to keys, built around your situation.
Send your statements
Recent bank statements usually tell the story. Tax returns help but aren't the only option.
Agree on a payment that fits your business
We look at your average monthly deposits, not your best or worst month, and size the home to fit.
Close and keep running your business
Your deed is recorded at closing. When your business history is longer, a bank-statement loan can refinance the note.
Who you're talking to
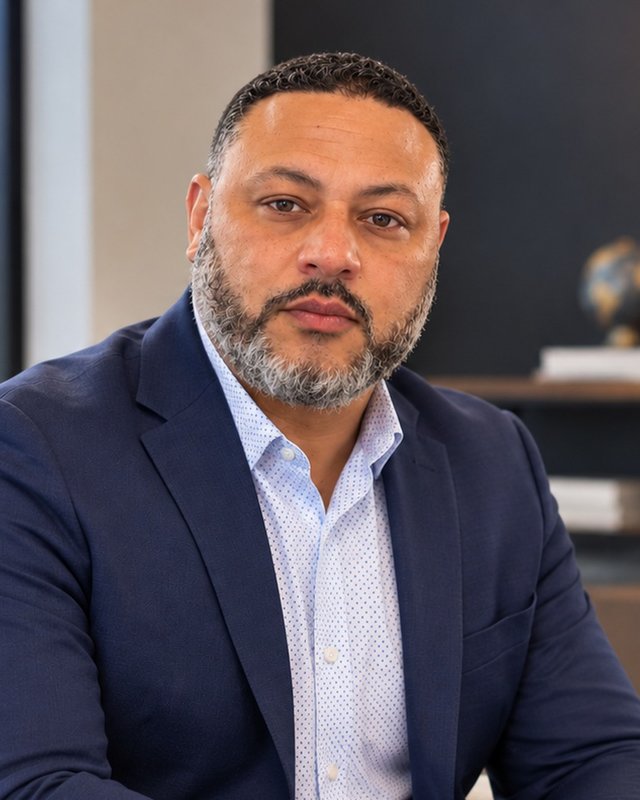
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy spent years in sales on commission before investing full time, so he knows what irregular income looks like when it's actually steady.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours.
- Bank statements instead of W-2s.
- 1099, gig and commission income count.
- No two-year same-employer rule.
- Refinance later with no penalty.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Questions we hear about this
Can I buy a house if I'm self-employed?
Yes. We qualify self-employed buyers using bank statements or tax returns. A W-2 job isn't required.
Do I need two years of tax returns?
No. We look at whether your income is steady and covers the payment.
Does 1099 or gig income count?
Yes. Rideshare, delivery, contract and commission income all count.
What if my tax returns show low income?
We can look at bank statements instead, which often show what you really earn.
Can I refinance later?
Yes, anytime, with no prepayment penalty.
Ready to stop renting?
Find out in about a minute whether the program fits you.