
Buy a Home With an ITIN, Without a Bank
Yes, you can buy a home with an ITIN number and no Social Security number. We qualify you on income and down payment, and the deed is yours at closing.
- No Social Security number needed
- No U.S. credit history required
- Deed in your name at closing
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Can I buy a house with just an ITIN?
Yes. An ITIN, an Individual Taxpayer Identification Number, is enough to buy a home through this program. You don't need a Social Security number, and you don't need a long U.S. credit history. What you need is steady income, a down payment, and a home you want to live in.
Some banks offer ITIN mortgages, but they usually want two years of U.S. tax returns, a credit history built here, and a higher rate. Many families who have been working and saving for years still get told no. Owner financing skips the bank entirely.
What we look at instead
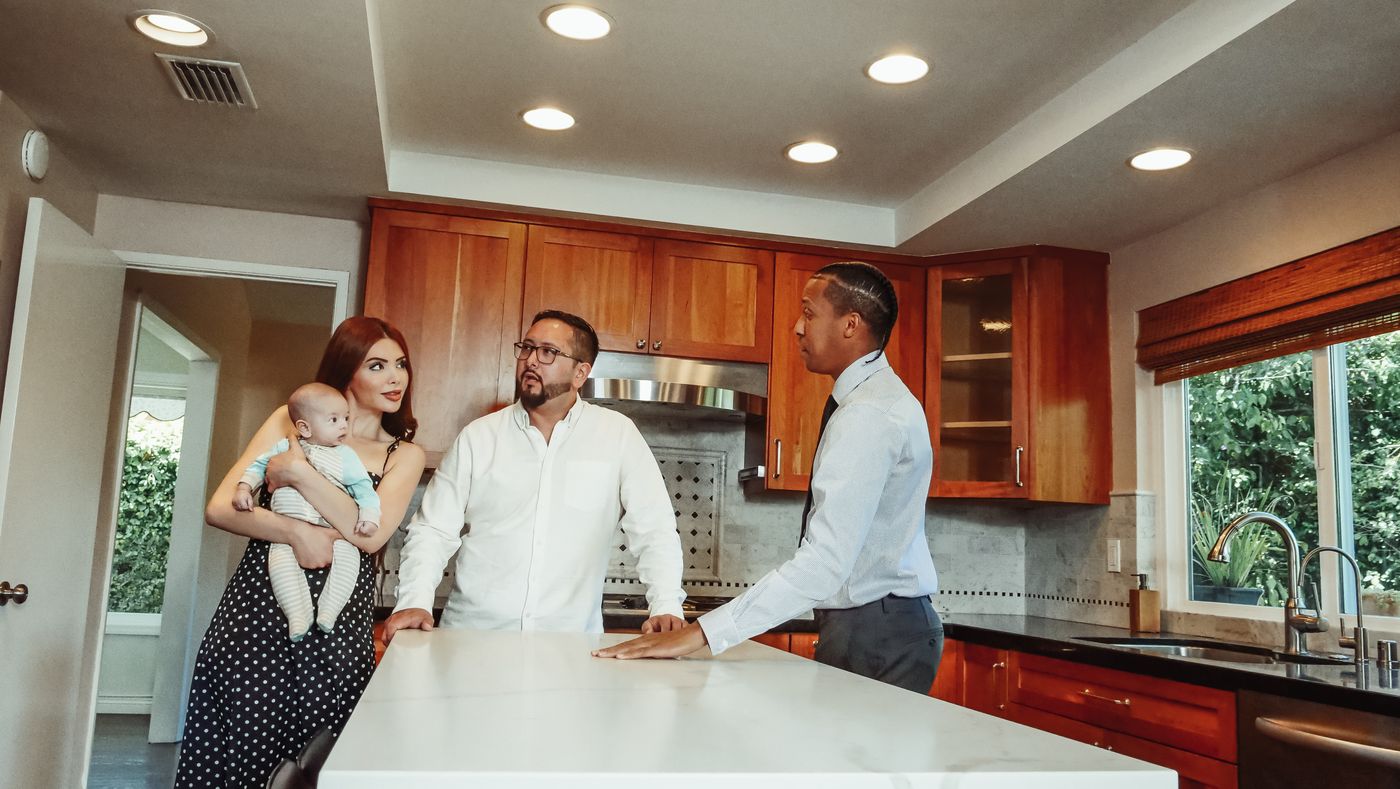
We look at three things. Your income: pay stubs, bank statements or tax returns filed with your ITIN all work. Your down payment: normally 20 percent of the price we negotiate, with exceptions reviewed one by one. And your stability: how long you've been working and living here, and whether the payment fits comfortably.
We also run a background check as part of qualifying. A thin or missing credit file isn't held against you.
Documents to have ready
A valid passport or government ID, your ITIN letter, recent bank statements, proof of income such as pay stubs, tax returns or 1099s, and proof of your down payment funds. If your savings are in cash, start depositing them into a bank account now, so the money shows up on statements before you buy.
Is the home really mine?
Yes. You close with a title company or closing attorney, and the deed is recorded in your name. Your immigration status isn't printed on a deed. You are the legal owner, you can sell or refinance later, and the home can pass to your family.
Building credit while you own
Many ITIN buyers have no U.S. credit file at all. Owning a home and paying on time is a strong start. Pair it with a secured credit card or a credit-builder loan from your bank, and in a year or two you may qualify for an ITIN mortgage that pays off the note at a lower rate.
How it works for you, start to finish.
Three steps from first call to keys, built around your situation.
Talk through your documents
Bring your ITIN letter, ID and bank statements. Freddy confirms what counts as income and how much you've saved.
Get your letter and pick a home
With a qualification letter good for 12 months, choose three homes. We negotiate for you.
Close with your name on the deed
A title company or attorney records the deed in your name. Your ITIN is all you need to own it.
Who you're talking to
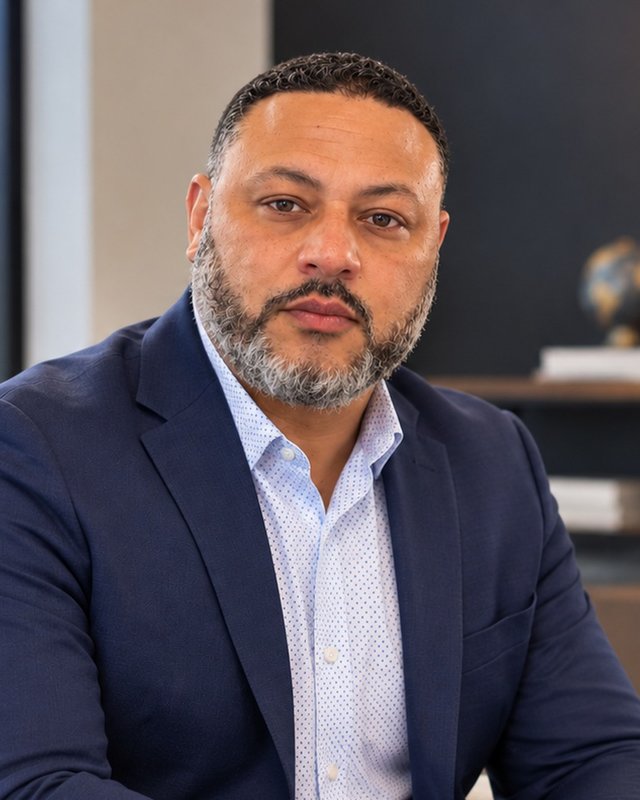
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Many of the families Freddy works with are building their first home in the U.S. He explains every document in plain words before you sign it.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours.
- No Social Security number required.
- No U.S. credit history required.
- Your name on the recorded deed.
- Refinance into an ITIN loan later if you want.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Questions we hear about this
Can I buy a house with an ITIN number?
Yes. In this program you can buy with an ITIN and no Social Security number. We qualify you on income, down payment and stability.
Do I need U.S. credit to buy with an ITIN?
No. There is no minimum credit score, and a missing U.S. credit file isn't held against you.
How much down payment do ITIN buyers need?
Normally 20 percent of the negotiated price, with exceptions reviewed one by one.
Can I refinance into an ITIN mortgage later?
Yes. There's no prepayment penalty. After a record of on-time payments, an ITIN mortgage or other loan can pay off the note.
Will my name be on the deed?
Yes. The deed is recorded in your name at closing.
Ready to stop renting?
Find out in about a minute whether the program fits you.