
Buy a House With Bad Credit, No Bank Needed
You can buy a house with bad credit when the financing doesn't come from a bank. There's no minimum credit score here, only steady income and a down payment.
- No minimum credit score
- Collections and late payments considered in context
- Refinance later as your credit recovers
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Can I buy a house with a 500 credit score?
In this program, yes, if your income comfortably covers the payment and you have the down payment. Banks use a credit score as a gate, and most conventional loans want 620 or higher. We use it as one piece of information, next to what you earn and save today.
A score can drop for reasons that say little about whether you'll pay for your home: a medical bill, a divorce, a job loss that's behind you, or simply never having used credit. We'd rather look at your last six months of bank statements.
What matters more than your score
Steady income that covers the payment without straining you. A down payment, normally 20 percent of the price we negotiate, with exceptions reviewed one by one. And a clean recent pattern: paying rent and bills on time lately counts for a lot.
What we can't work with is a pattern of not paying: repeated evictions or walking away from obligations. We run a background check, so it comes up either way.
A large down payment changes everything
Buyers with bad credit and real savings are often the best fit for owner financing. The down payment lowers the amount financed, which lowers the payment, which makes the deal work. The more you put down, the lower your monthly cost.
Rebuild your credit while you own
Once you own the home and make on-time payments, your situation keeps improving. There's no prepayment penalty, so when your score recovers you can refinance into a conventional loan at a lower rate.
Common reasons for a low score we see
Medical bills sent to collections, a divorce that split finances, a job loss that's now behind you, student loans, or simply a thin file. None of these stop you here if your income is steady and you have a down payment. What we look harder at is recent behavior: the last year of rent and bills.
A buyer Freddy helped
Travis K., a retired veteran, came to Freddy with a credit score around 520. He bought a four-bedroom home in Peoria, Illinois with $20,000 down, made 30 months of payments, and then refinanced into a VA loan. That was a past deal outside today's markets, but the path is the same one this page describes.
How it works for you, start to finish.
Three steps from first call to keys, built around your situation.
Show us today, not your score
Freddy looks at your last several months of income and bills. A low score is a conversation, not a rejection.
Use your down payment to your advantage
The more you put down, the lower your payment. We pick homes and terms that fit the payment you can carry.
Close, then rebuild
You own the home at closing. Pay on time, let your credit recover, and refinance when it makes sense.
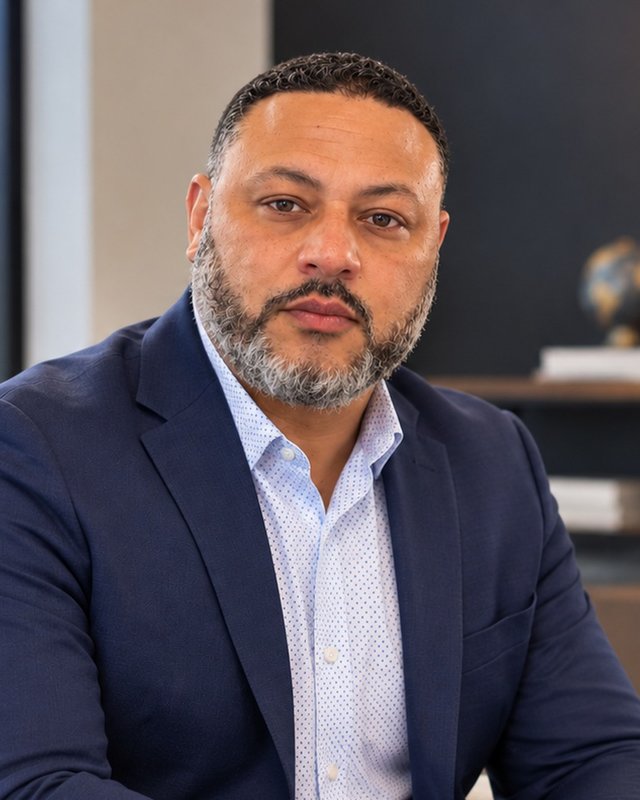
Who you're talking to
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy has watched good buyers get turned away over a number that didn't reflect how they pay their bills today. That's the reason this program exists.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours.
- No minimum credit score.
- Collections and late payments looked at in context.
- A bigger down payment lowers your payment.
- Refinance anytime, no penalty.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Questions we hear about this
Can I buy a house with bad credit?
Yes, through owner financing. There's no minimum credit score. We qualify you on income and down payment.
What credit score do I need for owner financing?
In this program, none. A low score by itself won't disqualify you.
Does a big down payment help with bad credit?
Yes. A larger down payment lowers the amount financed and the monthly payment.
Will owner financing help me rebuild credit?
Owning the home and paying on time puts you in a stronger position. When your credit recovers, you can refinance with no prepayment penalty.
Do you check credit at all?
We run a background check as part of qualifying, mostly to look for patterns like repeated evictions.
Ready to stop renting?
Find out in about a minute whether the program fits you.