
A Better Alternative to Rent to Own Homes
If you're looking at rent to own homes, there's a better alternative: owner financing puts the deed in your name at closing, so you own from day one.
- Own at closing, not someday
- Your payments build your equity
- No option fee you can lose
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
What's wrong with rent to own?
In a typical rent to own or lease option deal, you sign a lease, pay an option fee, and pay rent, sometimes with a credit toward a future purchase. The seller keeps the deed the entire time. If you don't qualify for a loan by the end of the lease, you usually lose the option fee and any rent credits.
The bigger risk is on the seller's side. If the seller stops paying their mortgage, files bankruptcy, gets divorced, or has a judgment or tax lien filed against them, the home can be lost, and you can lose it with them, even if you paid every month on time.
How owner financing is different
With owner financing you buy the home at closing. A title company or closing attorney records the deed in your name the same day. You make fixed monthly payments on a note, with no balloon payment and no prepayment penalty. You're the owner, so the seller's later problems are not your problems.
You also get the benefits of ownership right away: you build equity, you can claim your state's homestead or owner-occupant tax break, and you can sell or refinance whenever you choose.
Who rent to own still makes sense for
Rent to own can make sense if you have very little saved and need a year or two to build a down payment. Owner financing needs a down payment, normally 20 percent, with exceptions reviewed one by one. If you have that, there's little reason to rent a home you could own.
Questions to ask about any rent to own offer
Who is on the deed today, and is there a mortgage on the home? Is the seller current on that mortgage and on property taxes? How much of your rent counts toward the price? What happens to your option fee if you can't buy in time? If the answers aren't clear and in writing, that tells you a lot about the deal.
How it works for you, start to finish.
Three steps from first call to keys, built around your situation.
Compare the deal you were offered
Send us the rent to own terms you're looking at. We'll show you what owning the same kind of home would cost.
Put your down payment toward a purchase
Instead of an option fee you might lose, your money goes toward a home you own at closing.
Close with the deed in your name
A title company or attorney records your deed. No lease, no option deadline.
Who you're talking to
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
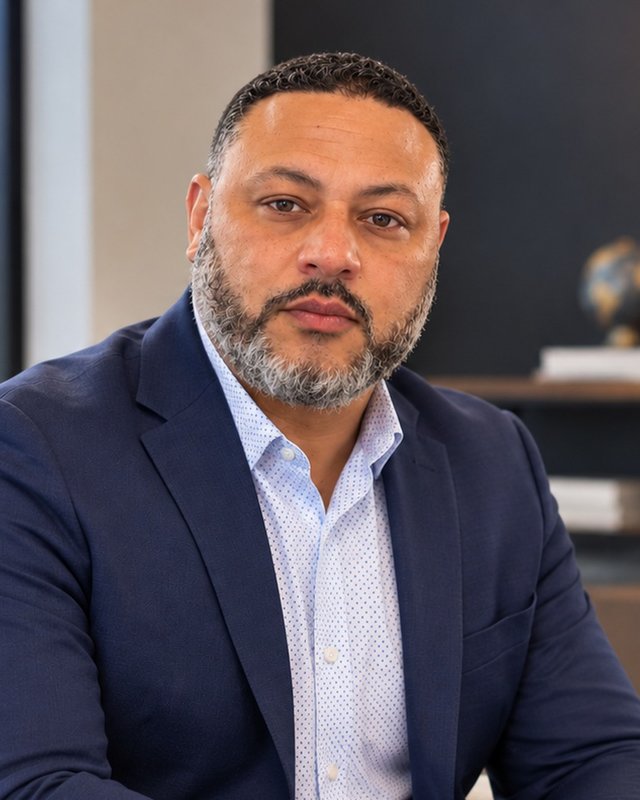
Freddy built this program after watching rent to own tenants pay for years and walk away with nothing. Owning at closing is the whole point.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify.
Answer a few quick questions. If the program fits, Freddy will reach out within 24 hours.
- Own at closing, not after a lease.
- No option fee to lose.
- Protected if the seller has money trouble.
- Claim your state's owner tax break.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Questions we hear about this
Is owner financing the same as rent to own?
No. With owner financing you own the home at closing and the deed is in your name. With rent to own you're a tenant until you buy later.
What happens to my option fee in rent to own?
In most deals, you lose it if you don't buy by the end of the lease.
Can I lose a rent to own home if the seller has problems?
Yes. If the seller's mortgage, liens or bankruptcy cause the home to be lost, a tenant usually has little protection.
Do I need a down payment for owner financing?
Yes, normally 20 percent, with exceptions reviewed one by one. It's credited to your purchase.
Can I get rent to own homes near me instead?
You can, but if you have a down payment, owner financing lets you own the same kind of home from day one.
Ready to stop renting?
Find out in about a minute whether the program fits you.