
Owner Financing vs Rent to Own
Owner financing vs rent to own comes down to one question: who owns the house. With owner financing, you do, from the day you close.
- Deed in your name at closing
- Equity from your first payment
- Protected if the seller has money trouble
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Side by side
Nine differences that decide who actually owns the house.
| Question | This program | Rent to own or lease option | Waiting for a mortgage |
|---|---|---|---|
| Who is on the deed | You, from the day you close | The seller, until you buy | You, once a lender approves you |
| What protects you | A recorded deed in your name | A lease and an option contract | A recorded deed in your name |
| If the seller files bankruptcy or gets a lien | Your ownership isn't affected | You can lose the home and your option money | Not applicable |
| Upfront money | A down payment credited to the price | An option fee that's usually lost if you don't buy | Down payment plus lender closing costs |
| Monthly payment | Fixed, building your equity | Rent, sometimes with a small credit | Fixed or adjustable, building equity |
| Owner-occupant tax break | Yes, you can apply | No, the landlord owns the home | Yes, you can apply |
| Repairs | Your choice, and they add to your equity | Often your cost, on a home you don't own yet | Your choice |
| Deadline pressure | None. No balloon, no option expiration | Buy by the end of the lease or lose your credits | Rate locks and underwriting deadlines |
| Credit score | No minimum | Often none to start, then a loan later | Usually 620 or higher |
How rent to own usually works
In a rent to own deal, also called a lease option or lease purchase, you sign a lease and pay an option fee for the right to buy later. You pay rent, sometimes with a small credit toward the price. The seller keeps the deed, and you're a tenant until you get a loan and buy.
If you can't get a loan by the end of the lease, you usually lose the option fee and any rent credit. And because the seller still owns the home, their problems can become yours: a missed mortgage payment, a bankruptcy, a divorce, a tax lien or a judgment can cost you the home even if you paid on time.
How owner financing works instead
With owner financing you buy the home at closing. A title company or closing attorney records the deed in your name. You sign a promissory note with a fixed monthly payment, and there is no balloon payment and no prepayment penalty.
You build equity from your first payment, you can sell or refinance whenever you choose, and the seller's later problems don't touch your ownership. See how it works step by step.
The tax break most people miss
Every state we serve gives people who own and live in their home a property tax advantage that renters can't claim. A rent to own tenant pays rent on a home taxed at the landlord's rate. An owner applies for the owner-occupant break the first year.
- Florida: property taxes and the florida homestead exemption
- Georgia: property taxes and the georgia homestead exemption
- Alabama: why owning lowers your alabama property taxes
- North Carolina: property taxes in north carolina
- South Carolina: the 4% legal residence rate
- Maryland: property taxes and the homestead tax credit
When rent to own still makes sense
If you have very little saved and need a year or two to build a down payment, a fair rent to own deal can be a stepping stone. If you already have 20 percent saved, there's little reason to rent a home you could own. See who qualifies.
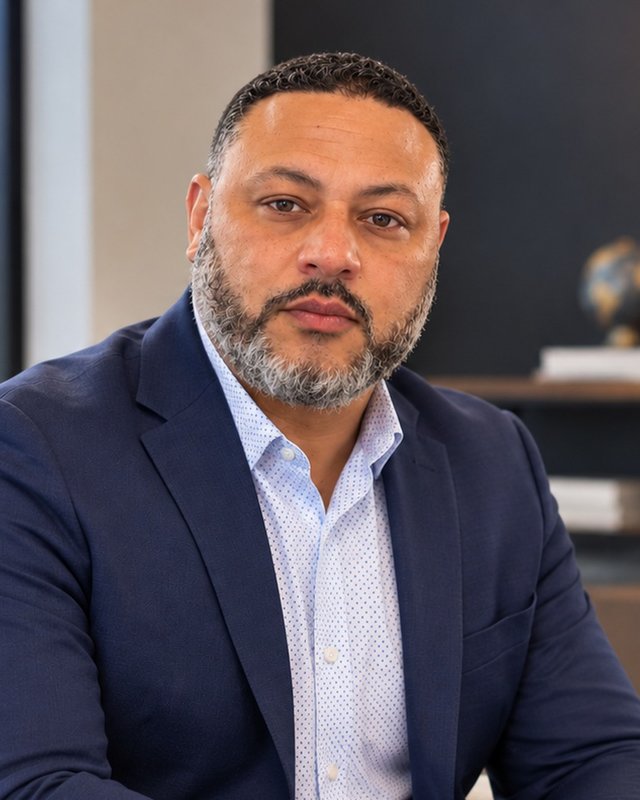
Why Freddy built this
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy kept meeting rent to own tenants who had paid for years and walked away with nothing when the lease ran out. Owning at closing fixes that.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you can own instead.
A few quick questions. If you have a down payment and steady income, Freddy will reach out within 24 hours.
- The deed is in your name at closing.
- There is no minimum credit score.
- Self-employed and 1099 income both count.
- ITIN holders are welcome.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Rent to own questions
Can I switch from a rent to own deal to owner financing?
Often, yes, if you have a down payment. Send us the terms you were offered and we'll show you what owning a similar home would look like.
Is owner financing more expensive than rent to own?
Usually it needs more money up front, because a down payment is larger than an option fee. Over time, owner financing builds equity while rent mostly doesn't.
What happens at the end of a rent to own lease?
You either get a loan and buy, or you usually lose the option fee and any rent credits. Owner financing has no lease deadline.
Which states give owners a tax break renters can't get?
All six states we serve tax owner-occupied homes differently. Florida and Georgia offer homestead exemptions, Alabama assesses owner-occupied homes at half the rental rate, South Carolina at 4 percent instead of 6, and Maryland caps yearly assessment increases. You need the deed in your name to claim them.
Ready to stop renting?
Find out in about a minute whether the program fits you.