
Owner Financing Homes in Baltimore, MD
Yes, you can buy owner financing homes in Baltimore, MD without a bank loan. You settle with a title company, and your deed is recorded in your name.
- Baltimore City and the surrounding county
- Hospital, port and contractor income welcome
- No minimum credit score
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Who this works for in Baltimore
Baltimore's hospitals, universities and port employ a huge share of the city, often on shifts and contracts that banks read the wrong way.
Hospital and university staff
Baltimore's medical and university systems are the city's biggest employers. Residents, travel nurses and contract staff have real income and short job histories.
Port and logistics workers
The Port of Baltimore and the warehouses around it run on shifts and overtime.
Federal contractors
Contract work around Fort Meade and the federal agencies near Baltimore pays well but changes often.
Rowhome renters ready to own
Many Baltimore renters already pay as much as a payment would cost. Owning puts that money toward a home of their own.
What a Baltimore home costs right now
Source: Redfin housing market data, three months ending September 2026.
Baltimore City's median sale price was about $230,000 in September 2026, and homes sold at about 101 percent of list, often with multiple offers. The program starts at $250,000, so buyers here look at the city's larger rowhomes and detached houses, or just over the county line. At 20 percent down, a $275,000 home needs $55,000.
This is a competitive market. Sellers here want certainty, so being qualified before you shop matters more in Baltimore than almost anywhere we work.
Where in Baltimore we help buyers
In the city, homes in range are mostly in Hamilton, Lauraville, Highlandtown and Ednor Gardens. Just outside the city line, Towson, Parkville, Perry Hall, Catonsville and Glen Burnie have far more homes above $250,000. Baltimore City deeds are recorded in the Baltimore City Circuit Court land records. Baltimore County and Anne Arundel County homes record with their own circuit courts.
For closing costs and tax breaks that apply across the state, see owner financing in Maryland.
Three steps to your Baltimore home.
What buying in Baltimore looks like from first call to keys.
Get your letter before you shop
Baltimore homes sell at or above asking. A 12-month letter lets you compete with buyers who have bank approvals.
Pick city or county homes
A larger city rowhome or a house just over the line. Three picks, so there's always a backup, negotiated for you.
Go to settlement
A title company or settlement attorney handles settlement and records your deed in the land records.
Tips for buying in Baltimore
Inspect older rowhomes carefully. Much of Baltimore's housing was built before 1978, so expect a lead paint disclosure and look closely at roofs, party walls and basements. A careful inspection protects your down payment.
Price in transfer and recordation taxes. Baltimore City's rates are among the highest in Maryland. We build them into your numbers so settlement day holds no surprises, and first-time Maryland buyers may get a break on the state portion.
Owner financing vs rent to own in Baltimore
Rent to own in Baltimore usually means renting a rowhome from an investor who keeps the deed. The tenant pays rent, often handles repairs, and has little protection if the investor falls behind.
With owner financing your deed is recorded at settlement. You can apply for Maryland's Homestead Tax Credit, and every payment builds your equity.
See every difference side by side on owner financing vs rent to own.
Cash to close on a Baltimore home
Starts at $250,000, where the program begins. Baltimore's median is lower, so slide up to the homes you're looking at.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
Your Baltimore contact
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
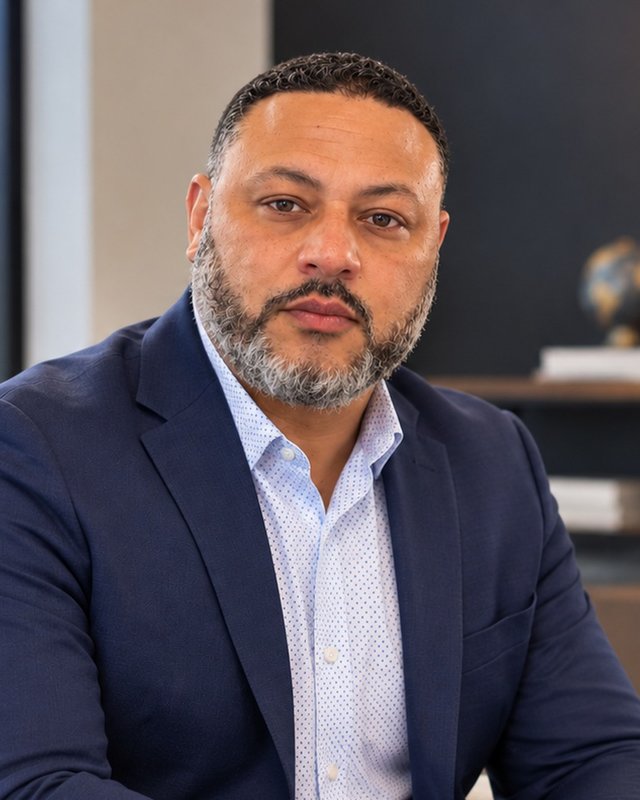
Freddy works with Baltimore-area buyers in the city and the surrounding counties, with every settlement handled by a title company or settlement attorney.
In Baltimore's competitive market, Freddy prices Maryland's transfer and recordation taxes into your numbers up front, so settlement holds no surprises.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify for a Baltimore home.
Tell us where around Baltimore you want to live and what you can put down. Freddy will reach out within 24 hours.
- Deed recorded with the Baltimore City Circuit Court land records.
- Homes from $250,000 in Baltimore City and nearby towns.
- You can apply for Maryland's Homestead Tax Credit, which caps yearly assessment increases.
- No minimum credit score.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Baltimore owner financing questions
Can I buy a Baltimore home with owner financing?
Yes. Pick a home in Baltimore City or the surrounding county from $250,000 up, and your deed is recorded in your name at settlement.
How much down do I need in Baltimore?
Normally 20 percent, with exceptions reviewed one by one. On a $275,000 home, 20 percent is $55,000.
Baltimore homes sell fast. Can owner financing compete?
Yes, if you're qualified first. Your letter shows sellers you're ready to settle.
Do you cover Towson, Perry Hall and Glen Burnie?
Yes, plus Parkville and Catonsville.
What are closing costs like in Baltimore?
Maryland and Baltimore City transfer and recordation taxes are among the highest in the country. We price them into your numbers before you choose a home.
What credit score do I need?
There is no minimum credit score.
Ready to own in Baltimore?
Find out in about a minute whether the program fits you.