
Owner Financing Homes in Charlotte, NC
Yes, you can buy owner financing homes in Charlotte, NC without a bank loan. A North Carolina attorney closes, and your deed is recorded in your name.
- Charlotte and the surrounding counties
- Contract and 1099 income welcome
- Attorney-handled closing
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Who this works for in Charlotte
Charlotte's banks hire thousands of contractors and its growth keeps the trades busy. That's a lot of good income that doesn't look like a bank's ideal file.
Finance and tech contractors
Charlotte's banking and tech employers rely on contract workers. Strong pay, short tenure, and a lender who wants two years of W-2s. We don't.
Construction and trades
The region keeps building. Electricians, framers and HVAC techs who own their business can qualify on bank statements.
Transplants with savings
People keep moving to Charlotte with savings and a credit history that doesn't follow them neatly. A down payment goes a long way here.
Families in East and West Charlotte
Rents have climbed across the city. If you can pay rent, you may be able to pay toward your own home.
What a Charlotte home costs right now
Source: Redfin housing market data, three months ending September 2026.
Charlotte's median sale price was about $420,000 in September 2026, with homes selling near 98 percent of list in under two months. At 20 percent down, a median home needs about $84,000.
Many buyers find better prices just outside the city, in Gastonia, Concord or Rock Hill across the South Carolina line, where the same down payment buys more house.
Where in Charlotte we help buyers
We cover University City, Steele Creek, East Charlotte and West Charlotte, plus Concord, Gastonia, Matthews, Mint Hill, Huntersville and Indian Trail. Deeds for Mecklenburg County homes are recorded with the Mecklenburg County Register of Deeds.
For closing costs and tax breaks that apply across the state, see owner financing in North Carolina.
Three steps to your Charlotte home.
What buying in Charlotte looks like from first call to keys.
Get your letter
Freddy reviews income and savings. Charlotte homes move in under two months, so a 12-month letter helps you act fast.
Pick homes across the region
Mecklenburg, Cabarrus, Gaston or Union County. Three picks, so there's always a backup, negotiated for you.
Close with an NC attorney
A North Carolina real estate attorney handles title and closing, and your deed records with the county Register of Deeds.
Tips for buying in Charlotte
Read the HOA documents in the suburbs. Many homes in Huntersville, Indian Trail and Steele Creek are in HOAs with their own fees and rules. We go over them with you before closing.
Look across the state line. Rock Hill and Fort Mill in South Carolina are part of the Charlotte metro, and they come with South Carolina's 4 percent owner-occupant tax rate. If the commute works, it's worth comparing.
Owner financing vs rent to own in Charlotte
Charlotte has a busy market in lease-purchase homes, many owned by large investors. The tenant pays rent and fees and the investor keeps the deed until a purchase that may never happen.
With owner financing your deed is recorded at an attorney-handled closing. Your payments build your equity in a market that's been one of the strongest in the Southeast.
See every difference side by side on owner financing vs rent to own.
Cash to close on a Charlotte home
Starts at Charlotte's September 2026 median sale price. Slide to the price of the homes you're looking at.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
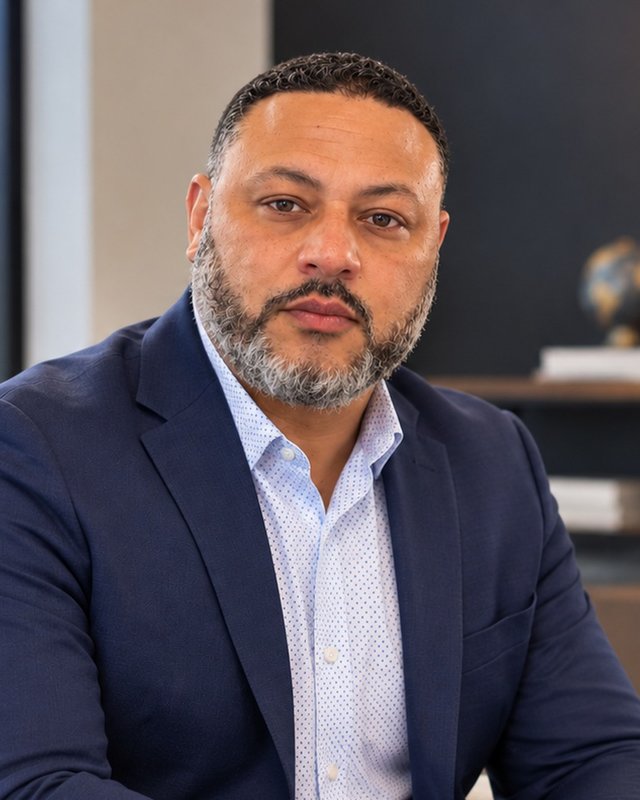
Your Charlotte contact
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy works Charlotte-area deals with North Carolina real estate attorneys handling every closing.
In Charlotte's quick market, Freddy gets your offer in fast and lets the North Carolina attorney handle title while he handles the seller.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify for a Charlotte home.
Tell us where around Charlotte you want to live and what you can put down. Freddy will reach out within 24 hours.
- Deed recorded with the Mecklenburg County Register of Deeds.
- Homes from $250,000 in Mecklenburg County and nearby towns.
- The seller pays North Carolina's excise tax, and the deed of trust isn't taxed.
- No minimum credit score.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Charlotte owner financing questions
Can I buy a Charlotte home with owner financing?
Yes. Pick a home in the Charlotte area from $250,000 up, and a North Carolina attorney closes with your deed recorded in Mecklenburg County or your home's county.
How much down do I need in Charlotte?
Normally 20 percent, with exceptions reviewed one by one. On Charlotte's September 2026 median of about $420,000, 20 percent is about $84,000. Homes in Gastonia or Concord often need less.
Can contract income qualify me?
Yes. We look at steady income and savings, not years with one employer.
Do you cover Concord, Gastonia and Matthews?
Yes, plus Mint Hill, Huntersville and Indian Trail.
Who handles closing in North Carolina?
A North Carolina real estate attorney normally handles title and closing.
What credit score do I need?
There is no minimum credit score.
Ready to own in Charlotte?
Find out in about a minute whether the program fits you.