
Owner Financing Homes in Columbia, SC
Yes, you can buy owner financing homes in Columbia, SC with no minimum credit score. Your deed is recorded in your name at an attorney-supervised closing.
- Columbia, Lexington and the Midlands
- Military and state employee income welcome
- 4% legal residence tax rate
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Who this works for in Columbia
Columbia is a capital city and an Army town, with a big university in the middle. That's a lot of steady paychecks attached to people who move often.
Soldiers and families at Fort Jackson
Fort Jackson trains thousands of soldiers a year. Families stationed here can own instead of renting near post.
State and university employees
Government and university jobs are steady but often start on contracts. We count that income.
Healthcare workers
The Midlands' hospitals run on shift work and travel contracts. Real income, unusual paperwork.
First-time buyers on a budget
Columbia is one of the more affordable cities we cover, so a down payment goes further.
What a Columbia home costs right now
Source: Redfin housing market data, three months ending September 2026.
Columbia's median sale price was about $273,000 in September 2026, and homes sold in about 41 days, the fastest pace of any city we cover. At 20 percent down, a median home needs about $55,000.
Fast markets reward buyers who are ready. Getting your letter first is the difference.
Where in Columbia we help buyers
We cover Columbia and the Midlands: Forest Acres, West Columbia, Cayce, Lexington, Irmo, Chapin and Blythewood. Deeds for Richland County homes are recorded with the Richland County Register of Deeds. Lexington County homes record with the Lexington County Register of Deeds.
For closing costs and tax breaks that apply across the state, see owner financing in South Carolina.
Three steps to your Columbia home.
What buying in Columbia looks like from first call to keys.
Get your letter first
Homes in Columbia sold in about six weeks. With your 12-month letter, you can offer right away.
Pick homes across the Midlands
Richland or Lexington County. Three picks, so there's always a backup, negotiated for you.
Close under an SC attorney
Your closing is attorney-supervised and your deed records with the county. Then apply for the 4% rate.
Tips for buying in Columbia
If you're military, plan for orders. Buying near Fort Jackson makes sense even if you'll move, because you can rent the home out later. Just know the 4 percent rate only applies while it's your legal residence.
Check which county you're buying in. Richland and Lexington counties set different tax rates and school districts. The same price can mean a different monthly cost.
Owner financing vs rent to own in Columbia
Around Fort Jackson, rent to own is often pitched to military families who expect to move. If orders come before the purchase, the option fee is usually lost and the family never owned anything.
With owner financing you own from day one. If you move, the home is still yours to sell, rent or refinance, and while you live there you can claim the 4 percent rate with the county assessor.
See every difference side by side on owner financing vs rent to own.
Cash to close on a Columbia home
Starts at Columbia's September 2026 median sale price. Slide to the price of the homes you're looking at.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
Your Columbia contact
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
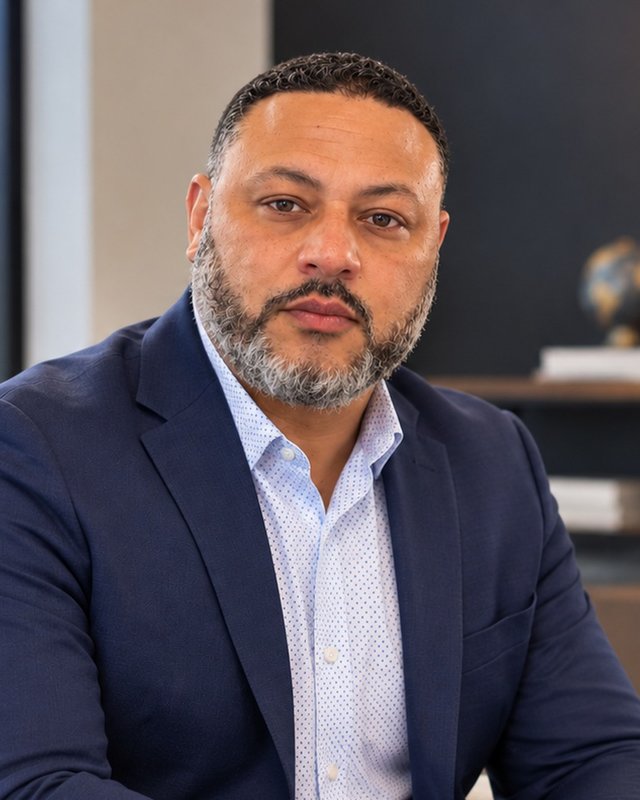
Freddy works with Midlands buyers, from military families to state employees, with closings supervised by South Carolina attorneys.
For Midlands buyers, including military families, Freddy plans closings around report dates and moves so you aren't paying rent and a payment at once.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify for a Columbia home.
Tell us where around Columbia you want to live and what you can put down. Freddy will reach out within 24 hours.
- Deed recorded with the Richland County Register of Deeds.
- Homes from $250,000 in Richland County and nearby towns.
- You can apply for South Carolina's 4 percent legal residence rate instead of 6 percent.
- No minimum credit score.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Columbia owner financing questions
Can I buy a Columbia, SC home with owner financing?
Yes. Pick a home from $250,000 up, and your deed is recorded in your name at an attorney-supervised closing.
How much down do I need in Columbia?
Normally 20 percent, with exceptions reviewed one by one. On Columbia's September 2026 median of about $273,000, 20 percent is about $55,000.
Do you work with military families at Fort Jackson?
Yes. You own the home at closing, so a move doesn't cost you what you put in.
Do you cover Lexington and Irmo?
Yes, plus West Columbia, Cayce, Forest Acres, Chapin and Blythewood.
Can I get the 4% tax rate?
Yes, if you own and live in the home and apply with your county assessor.
What credit score do I need?
There is no minimum credit score.
Ready to own in Columbia?
Find out in about a minute whether the program fits you.