
Owner Financing Homes in Charleston, SC
Yes, you can buy owner financing homes in Charleston, SC, North Charleston and Mount Pleasant without a bank loan. An attorney supervises closing, and the deed is yours.
- Charleston, North Charleston, Mount Pleasant
- Port, base and aircraft plant income welcome
- 4% legal residence tax rate
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
- Deed in your name at closing
- No balloon payment
- No minimum credit score
- ITIN holders welcome
Who this works for in Charleston
The Lowcountry's port, its joint base and its aircraft plant employ thousands, and a lot of them earn more than enough to own but still get turned down.
Joint Base Charleston families
Air Force and Navy families who'd rather build equity in North Charleston or Goose Creek than keep renting between assignments.
Port and logistics workers
The Port of Charleston's terminals and warehouses run on shifts and overtime. Steady hours are steady income.
Aircraft plant and supplier workers
The aircraft plant in North Charleston and its suppliers pay well, with contract roles and overtime a lender may discount.
Hospitality and healthcare workers
Downtown's restaurants, hotels and hospitals run on tips, shifts and travel contracts. We read the deposits.
What a Charleston home costs right now
Source: Redfin housing market data, three months ending September 2026.
The city of Charleston's median sale price was about $660,000 in September 2026, one of the highest of any city we cover, and homes took about 72 days to sell. Most of our Lowcountry buyers look in North Charleston, Summerville, Goose Creek and Ladson, where prices sit well below the city figure.
Longer market times give buyers room. Sellers who've waited two months or more are more open to a negotiated price.
Where in Charleston we help buyers
We cover Charleston, West Ashley, James Island and Johns Island, plus Mount Pleasant, North Charleston, Hanahan, Goose Creek, Ladson and Summerville. Deeds for Charleston County homes are recorded with the Charleston County Register of Deeds. Berkeley and Dorchester County homes, including most of Goose Creek and Summerville, record with their own county.
For closing costs and tax breaks that apply across the state, see owner financing in South Carolina.
Three steps to your Charleston home.
What buying in Charleston looks like from first call to keys.
Get your letter
Freddy reviews income and savings. Your letter is good for 12 months.
Pick three homes in the Lowcountry
North Charleston, Summerville, West Ashley or Mount Pleasant. We negotiate price and terms, and check flood zones first.
Close under an SC attorney
Your closing is attorney-supervised and your deed records with the county. Then apply for the 4 percent rate.
Tips for buying in Charleston
Get a flood zone answer on every home. King tides and storms flood parts of the peninsula, James Island and West Ashley, and flood insurance can change your monthly cost more than price.
File for the 4 percent rate right after closing. In Charleston County, a legal residence is also exempt from school operating taxes, and the savings only start once you apply.
Owner financing vs rent to own in Charleston
In the Lowcountry, rent to own tenants often pay rent on homes taxed at South Carolina's 6 percent rate, with the landlord keeping the deed and the tax savings.
With owner financing you own at closing and can apply for the 4 percent legal residence rate with the county assessor. In a market priced like Charleston's, that difference is real money every year.
See every difference side by side on owner financing vs rent to own.
Cash to close on a Charleston home
Starts at Charleston's September 2026 median sale price. Slide to the price of the homes you're looking at.
The program starts at $250,000 and has no upper limit. Down payments are normally 20 percent, with exceptions reviewed one by one. There's no application or origination fee.
- Down payment (20%)
- Closing costs (2% to 3%)
- Amount financed
Estimate only. Closing costs vary by state and are listed on your closing statement before you sign.
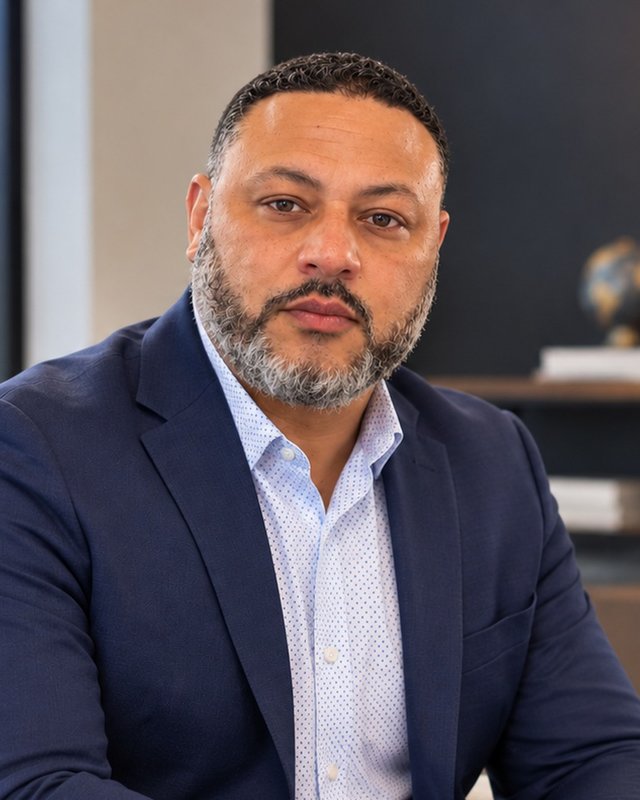
Your Charleston contact
- In real estate since 2010
- Finance degree, FIU
- 20+ families into homes since 2024
- Based in Fort Lauderdale, FL
- Speaks Spanish fluently
Freddy has closed deals in the Carolinas and works with Lowcountry buyers, with every closing supervised by a South Carolina attorney.
In the Lowcountry, Freddy checks the flood zone and the tax status on every pick, and reminds you to file for the 4 percent rate after closing.
"If you can afford the house, there should be a path to it."
Freddy E.Founder, Sold With Financing
See if you qualify for a Charleston home.
Tell us where in the Lowcountry you want to live and what you can put down. Freddy will reach out within 24 hours.
- Deed recorded with the Charleston County Register of Deeds.
- Homes from $250,000 in Charleston County and nearby towns.
- You can apply for South Carolina's 4 percent legal residence rate instead of 6 percent.
- No minimum credit score.
See if you qualify
Takes about a minute. Freddy replies within 24 hours.
Charleston owner financing questions
Can I buy a Charleston home with owner financing?
Yes. Pick a home from $250,000 up anywhere in the Charleston area, and your deed is recorded in your name at an attorney-supervised closing.
Do you cover North Charleston and Mount Pleasant?
Yes, plus West Ashley, James Island, Hanahan, Goose Creek, Ladson and Summerville.
Charleston prices are high. Where do buyers look?
Most look in North Charleston, Summerville, Goose Creek and Ladson, where homes cost far less than the city median.
Do I need flood insurance?
Many Lowcountry homes sit in flood zones. We check the zone and get a quote before you pick a home.
Can I get the 4% tax rate?
Yes, if you own and live in the home and apply with your county assessor before the first penalty date for the tax year.
What credit score do I need?
There is no minimum credit score.
Ready to own in Charleston?
Find out in about a minute whether the program fits you.